Sunday, January 31, 2010

Corporate Political Money Is Harmless

A recent article in the Times — bless some reporter’s or editor’s contrarian heart – asks the question: so, what effect does corporate money actually have on democracy?” The answer seems to be: none at all. One of the economists cited is Peter’s Missouri colleague, and my former student, Jeff Milyo: "There is just no good evidence that campaign finance laws have any effect on actual corruption."
The above excerpt is from "Apocalypse Averted" by Dick Langlois on Organization and Markets.

From the New York Times article mentioned in the above quote:
Justice Anthony M. Kennedy noted in his opinion that no evidence was marshaled in 100,000 pages of legal briefs to show that unrestricted campaign money ever bought a lawmaker’s vote. And even after Congress further tightened the rules with the landmark McCain-Feingold law in 2002, banning hundreds of millions of dollars in unlimited contributions to the political parties, public trust in government fell to new lows, according to polls.

And what about the corporations that contributed so much of that money? A review of the biggest corporate donors found that their stock prices were unaffected after they stopped giving to the parties. The results suggest that those companies did not lose their influence and may have been giving "because they were shaken down by politicians," said Nathaniel Persily, a professor at Columbia Law School who has studied the law’s impact.

"There is no evidence that stricter campaign finance rules reduce corruption or raise positive assessments of government," said Kenneth Mayer, a professor of political science at the University of Wisconsin-Madison. "It seems like such an obvious relationship but it has proven impossible to prove."

Saturday, January 30, 2010

Markets Predict A US Bond Default More Likely Than Coca-Cola Default

Trading in the credit-default swap market this week shows that investors now view a default by the U.S. Treasury as more likely than a default by the Coca-Cola Company....Now the United States has taken its place next to Italy and Spain in a special club that no major country wants to join -- countries whose debt is considered less safe than that of Blue Chip businesses.
from the Wall Street Journal article, "In Coke We Trust" by James Freeman.

Have Presidential Economic Advisers And The CEA Outlived Their Usefulness?

In 1946, after WWII, with fresh memories of the Great Depression, faith in Keynesian economics and a belief in successful government intervention in the economy, Congress passed the Employment Act of 1946 and established the Council of Economic Advisers (CEA) to advise the President.

As stated on Whitehouse.gov:
The Council of Economic Advisers assists the President with the development and implementation of our nation’s economic policy. Led by a Chair and two members, the Council consists of a team of highly-trained professional economists, forecasters and statistical experts who draw upon evidence-based research to provide the President with thorough and timely economic analysis. Christina Romer was appointed by President Obama and confirmed by the Senate to serve as Chair of the Council. Austan Goolsbee and Cecilia Rouse have been confirmed to serve as the Council’s two members.
In 1978, Congress passed the Humphrey-Hawkins law. It required the President to seek the inconsistent economic goals of full employment without inflation. The CEA's annual economic report on the economy, employment and jobs became a political document as it presented the President's goals for employment and economic growth in a favorable future scenario in accordance with electoral party economic platforms.

These days the political parties have opposing opinions of the effects of government intervention and taxes on economic growth and employment based on their different ideologies. The CEA's report and advice to the President is often just a restatement of his/hers party's prior philosophical and economic beliefs of the power of government intervention and the economic effects of taxes, supplemented with charts, graphs and numerical projections.

Past CEA chairs have said in substance that when they were advising the President, an economic policy's ability to get public acceptance and Congressional votes for passage was the paramount practicality and it overrode economic theory and research results.

Since Presidential political parties' economic policies reflect their ideologies, there is very little need to advise a President regularly on economics. Additionally, Congress can and often does hold hearings for new legislation where experts testify. The best minds and experts in economics can present their views and research in person or in writing at those times. Similarly, as the President does on other matters, there is nothing to stop him from hearing the views of economists and other economic advisers, which is what Presidents did before the CEA.

Other than producing documents and charts for other economists to accept, reject, criticize or defend, there is little purpose these days for the CEA. Regulatory issues, such as restructuring the financial system fall under the Treasury Secretary and not the CEA.

There is little reason these days to package ideologies in an economic paper of charts and numbers signed and presented by CEA members. It is time to stop the political charade and just abolish the CEA.

Friday, January 29, 2010

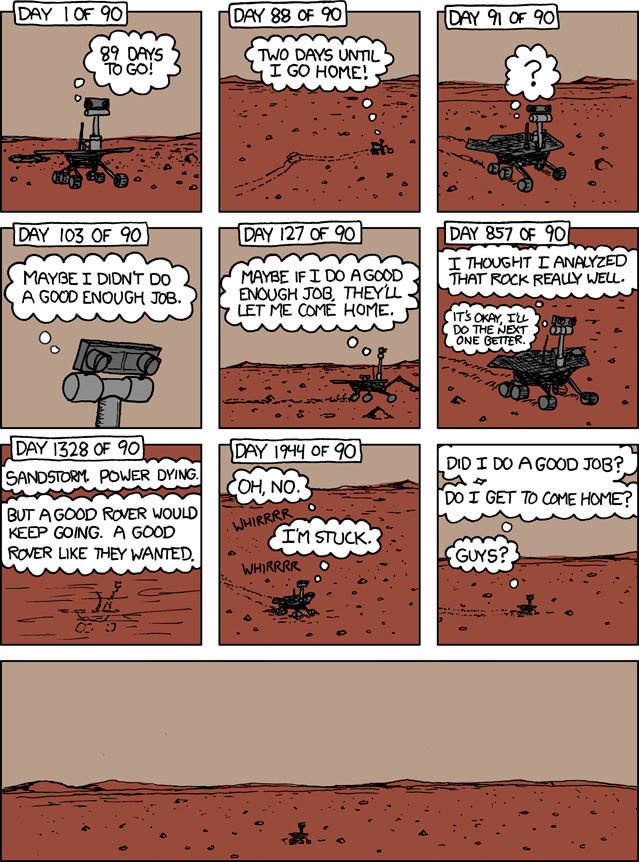
In Honor Of Mars Rover Spirit: Great Job!

Spirit from XKCD:


Thanks to all the people who conceived, designed, built, programmed and managed the Mars rover Spirit over the years.

Is it too much anthropomorphism to send Eve?

Thursday, January 28, 2010

US Unemployment Reduction Worse Than Other Countries

Rebecca Wilder on News N Economics blog posted charts showing that relative to each country's previous levels of unemployment, current US unemployment levels are worse than Asia, Emerging Europe and other G7 countries with the exception of Latvia.

See Rebecca's wonderful charts in her blog post, "Unemployment rates: U.S. versus the rest of the world."

The economic policy question of the day is why is the US experiencing worse unemployment and slower job growth than most developed countries and what can be done to create faster job growth?

Do Not Burst Bubbles: The Alternative Universe To Compare Economic Results Does Not Exist

EMH [Efficient Market Hypothesis] does not say anything about fundamental values because fundamental values are an undefined term. Fundamental values seem relevant after the fact because we focus on the particular meaning that makes the price appear over valued.

For example, for stocks, there are many 'fundamental value' criteria. Is it price to earnings, price to dividends, price to sales, price to cash flow, price to free cash flow, Gordon dividend growth model (with what growth rate), discounted cash flow (what growth rate, what discount rate), price to EBIT, price to competitor ratios, breakup value, etc.

For options, you write, "Event studies such as these are not quite enough to address Hanson's concern, since they do not consider false alarms: situations in which the prices of options signaled an increase in volatility that did not eventually materialize."

You are saying if I call the fire department everyday, and if one of those days my house is on fire, I have a good strategy. [I should have said people who call for the Fed to burst bubbles instead of 'you'.] Using implied option volatility that does not lead to a bubble collapse means, the Fed will do the wrong thing many times in order to make sure it does the right thing in a bubble. That is like telling a surgeon to cut into everyone to remove his or her appendix to prevent appendicitis. How many unnecessary recessions and periods of high unemployment are you willing to endure to prevent one bubble?

EMH says several things, but two important ones are:

It says past prices and past gains are irrelevant for determining the future gains and prices tomorrow, next week, next year, etc.

It says public information, including past public information, in addition to price information does not give you any ability to generate a better return than anyone else can or to tell what the price will be in any future time period.

Hindsight is wonderful. It tells the quarterback (The Fed) what play (money supply, interest rate policy) he should not have done. It does not guarantee that a different action would succeed. Many say Fed's loose money policies caused the housing bubble. Do we know that a tight money policy at that time would stop the housing bubble?

Even if we can call a bubble as it is happening and the Fed acts and the bubble crashes, is the economy worse or better off than if the bubble crashes without Fed action? Without a bubble, could we put ourselves in a worse economy than we currently are? We do not know. No models or predictors of the bubble crash predicted the severity of this recession. Without the ability to predict this recession from a bubble burst, how do we know it would not have been worse without the bubble?

How do we know that any Fed action to reduce asset prices in a bubble (housing), will only affect that asset (housing) and not other assets not in a bubble. Could the remedy cause a deflationary spiral across many assets and be worse than the bubble?

What do we gain and lose by interfering with bubbles? If we had stopped the dotcom bubble, would we have never had companies such as Amazon and EBay, to name two, or Google years later?

The alternative universe for us to compare economic results does not exist. We will never know if the proposed cure works or does not, or if the economy is better or worse for bursting a bubble.

I posted the above as a comment on Rajiv Sethi: thoughts on economics, finance, crime and identity... Blog, "Identifying Bubbles."

Bacteria Modifed To Produce Oil

Researchers have engineered a common type of bacteria to produce biodiesel and other goodies from plain old plants. The microbial trickery, detailed today in the journal Nature, promises to add "nature's petroleum" to America's energy supply within the next few years.
From "Bacteria rebuilt to make oil" by Alan Boyle.

After Foreclosure, Lenders Go After Former Homeowners For Unpaid Balances

Amid a crisis that stripped $6.4 trillion, or 28 percent, from the value of U.S. residential real estate since the 2006 peak, lenders are exercising their rights to pursue unpaid mortgage balances. To get their money, they can seize wages, tap bank accounts and put liens on other assets held by debtors.
From Bloomberg, "Lenders Pursue Mortgage Payoffs Long After Homeowners Default" By Kathleen M. Howley.

Wednesday, January 27, 2010

Is The Future Safety Net Multiple Jobs At Multiple Employers?


The above chart is from the New York Times article, "Job-Juggling and Job Loss" by Catherine Rampell.

States that have the highest percentage rate of workers with multiple jobs have the lowest unemployment. How will current and future workers respond to this severe economic downturn and high unemployment? Will they modify their behavior and hold multiple jobs from multiple employers as a way to diversify away the risk of a long-term loss of wages?

Certainly, at the non-professional level where job pay is hourly, it makes sense to diversify employers and hold two or more jobs from different companies. Does it make sense for managerial and professional workers who get a set weekly or yearly salary independent of the hours worked?

In the current recession where many white collar managers, lawyers, and other professionals are losing their jobs, facing long term unemployment and extended periods of lost wages, it would also make sense for them to have jobs at multiple employers and maybe also in multiple fields and sectors. Of course, there are logistical and structural issues to overcome, but nothing that is insurmountable.

Is the future of US employment, full workweeks through multiple part-time jobs at multiple employers? It is a possibility.

If employers benefit from full time employees over part-timers, employers will pay a premium wage for full time workers to offset the value of diversification to employees. Of course, there is a chance employers will find the lower wages of part-timers more valuable than having full time employees. It will come down to how risk adverse future employees become after this economic downturn and how important salary reduction is to employers across a wider range of job categories.

Will employees value a safety net of multiple employers in multiple sectors and fields over the higher wage premium of single employers?

Will employers value the lower wages of part timers more than the additional company value of a full time employee?

The next decade will tell. Either is a possible outcome.

Auotmatic Federal Tax Increases Next Year

...next year there will also be substantial tax increases for a great many Americans. The first reason will be the expiration of the Bush tax cuts. The top personal income tax rate will rise next Jan. 1 to 39.6% from 35%, a hike of nearly one-eighth. The dividend tax rate will rise to 39.6%, more than 2½ times the current 15%. And the capital gains tax rate will rise by a third, to 20% from 15%. If the House health care bill had passed, all three of these rates would have risen to 45%.

The estate tax, which fell to zero this year under the Bush tax cuts, will return in 2011--or sooner, if Congress acts to restore it. Another likely tax increase will be on the income of private equity and hedge-fund managers, from the capital gains rate of 15% to the new higher income tax rates. It has already been passed by the House and is supported by the Obama administration, as is an additional 10-year, $90 billion tax on banks aimed at "rolling back bonuses for top earners." It would affect some 50 banks, insurance companies, and large broker-dealers.

Meanwhile a number of last year's tax deductions have disappeared due to the failure of Congress to extend them into this year. The tax deduction for state and local sales taxes is one; the deduction for college tuition and fees is another; and the 50% write-off for small businesses for capital purchases--equipment, machinery or building a new plant--has disappeared as well, which will have a negative effect upon the construction of new business operation facilities.
From The Wall Street Journal opinion piece, "An Economic Time Bomb" by Pete Du Pont.

Tuesday, January 26, 2010

Obama-Volcker Rule Will Not Prevent A Future Financial Crisis

If an institution has a high risk tolerance, then limiting leverage, a firm's size, and its activities will not reduce the riskiness of the firm.

As a simple example, suppose a financial institution has one asset category, residential real estate loans (mortgages) totaling $100. Suppose the bank is a prudent lender and requires a 50 percent downpayment for every mortgage (a 2 to 1 leverage ratio for the borrower). The bank's $100 of mortgages is backing $200 of homes. If the bank has $3 of equity, its leverage ratio is 33.3 to 1, $100 of loans to $3 of equity. The house price risk the bank undertook is leveraged 66.7 to 1. $200 of real estate collateral is backed by $3 of equity.

Suppose we require the bank to hold twice as much capital, $6 of equity instead of $3 for each $1 of loans. Does the bank keep it 50 percent downpayment requirement or does it reduce the downpayment?

If the bank wants the same risk, it will reduce the downpayment requirement for its mortgages to 25 percent. Now, its $100 of mortgages will back $400 of home value, and the bank's leverage ratio will look better, 100 to 6, 16.7 ratio, instead of 100 to 3, a 33.3 ratio. The risk though will be the same because $400 of real estate value is backed by $6 of equity for a ratio of 66.7. The bank has the same home value risk as before.


The value of a collateralized loan is dependent on both the expected default rate and the value of the collateral. If default rates increase, the value of the loan portfolio decreases. If the collateral value decreases, the loan portfolio value decreases. If both happen simultaneously, there is a greater loan value decrease than from either alone. If default rates correlate with collateral value, there will be further declines in portfolio value over and beyond those that occur if default rates are not correlated with asset values. During the crisis, some of the CDOs held by Bear Stearns and others lost 70 percent or more of their value, while still being current in principal and interest payments.

In real financial institutions with many categories of loans and investments, some collateralized and some not, it will be impossible for regulators to monitor or prevent the shift in to higher asset risk with a lower leverage ratio.

Accounting values will never capture all loan or bank asset risk. There is, as in the example above, hidden leverage. Additionally, there are embedded options in assets and loans that increase their riskiness over their dollar amounts. Also, there are co-movements, correlation, effects that are not easily recognizable by regulators.

The regulators will never see full interconnectedness. In one part of the country, a bank could be lending to a homebuilder while another bank is lending to the buyers of those homes. The two banks could be in different parts of the country, lending to different groups (buyers and builders), and yet the banks are interconnected in their fates. A third bank could be lending to a business that likes to open near new home developments. The third bank's fate is bound to the first two.

There is also asymmetric information risk between the regulator and the bank. Can a regulator distinguish the riskiness of different small businesses, related businesses, new ventures, similar loans to different geographical areas, different economy sectors?

Banks can always increase or decrease the risk of their assets to keep the institutions' riskiness constant as regulators change leverage ratios.

There is an unresolved aspect of the recent financial crisis that might help to determine how governing bodies should proceed.

Did the banks think their risk was lower than it actually was? In other words, did they, the markets, the regulators and others honestly believe that the real estate investments (mortgages, CDOs, MBSs, etc.) were safe investments that could be highly leveraged to realize more risk, but one that remained after increased leverage, a modest and a safe risk for the bank? Alternatively, did they have a high risk appetite, recognize the amount of risk they were taking and gamble and lose?

If the bankers, the markets, individuals and the regulators did not see the risk, then we had an unexpected earthquake in an area that never has earthquakes. Whatever we do to prevent future earthquakes will not prevent future unexpected events from happening, such as a lightning strike or a tsunami. Future financial market crises become an unpleasant fact like a rare lightning strike. Even those who say they saw a real estate bubble never expected the severity of the financial crisis, the failure of firms, and the extent of the economic downturn.

If bankers, individuals (remember they were the ones with the insatiable demand for homes and home loans) businesses, and possibly government saw the risk, gambled and lost, we have to focus on why the economy's risk tolerance rose. Without an understanding of what created higher risk tolerance, government and regulator attempts to reduce institutional risk will fail. Controlling size or allowing failures will not be enough. The institutions will find ways through regulatory arbitrage, asymmetric information, embedded, and non-observable risks to keep their riskiness at a high level. The regulator will be a cat who can never catch the mouse. Future financial crises from high risk will continue to occur despite regulatory efforts.

Part of the regulatory solution begins by recognizing that future catastrophic financial events will occur unexpectedly, despite best analysis and modifications to regulatory and institutional structure, creating huge losses to financial institutions and harming the real economy.

Governments and regulators need better plans for after the fact damage control to the economy and financial institutions whether or not it is unpreventable. We need to develop solutions to keep business and consumer lending available, and to minimize and undo all the other foreseeable negative financial and real economy effects that occur during and after a financial crisis.

While attempts to prevent financial crises is admirable, we may achieve more economic success by assuming they will occasionally occur and developing the equivalent of fire departments and the Red Cross to deal with situations after a crisis occurs.

Originally, governments and economists thought institutions like the Federal Reserve, Bank of England, etc. were enough of a fire department and aid organization. We need to rethink that philosophy and see if we need additional organizations or tools for future crises.

The above is a comment I posted on VOX blog, "Too interconnected to fail = too big to fail: What is in a leverage ratio?" by Danile Gros.

[Also see my other post: "Obama's New Bank Restrictions Increase Systemic Risk"]

Monday, January 25, 2010

Why Good Schools And Poorly Performing Schools Stay That Way: Survivorship, Selection, Retention And Filtering Bias

I am in favor of more information about schools, teachers and student educational performance because I believe there is not enough accountability by school systems for the educational performance of students and because I believe desirable outcomes should be measured to allow for corrective feedback at all levels of the organization, including school, teacher and student.

I would think that parents and educators would want information that measured performance and also allowed for corrective actions. Too much information or the wrong set of information is not helpful.

It is individual teacher and individual student level longitudinal (over time) information, which is almost never forthcoming in any disclosure by school systems, that best measures a student's and a teacher's performance. Has the teacher been able to improve the student's performance over the year? Yes, good school for that student: No, bad school for that student.

A large data set of information maybe interesting for conversational topics but is costly both to the parents and the schools, in the sense that both must expend effort in learning which data is useful information for improving student performance and which data is extraneous information.

The problem with aggregated non-specific student and non-specific teacher information is that over any time period the students and the teachers change and comparisons of increasing or decreasing test scores are made against two different groups. This year's graduating students with teacher group A are compared to last year's graduates with teacher group B, for example, without knowing if comparison of the two groups is valid.

There are indications in educational performance data that there is selection and filtering bias, which interferes with the usefulness of the information for parent decision-making. For example, schools with high scores tend to demand a commitment to more schoolwork than lower performing schools and also over other student interests. Do parents and children who want more schoolwork move into these school areas and produce higher test scores or do the schools and teachers. Whether better performing schools, in the sense of higher student scores, attract better achieving students or produce better achieving students is often ambiguous from most studies of performance. Do good students make schools look better on tests or do good schools make students look better on tests?

There are also indications that schools signal which students they want to enroll, which students they want to keep, and which students' families they want to move to another school area. In the US, it is sometimes as simple as whether the school highlights the winning science fair participants or the football team, but often the signals are much more subtle and less obvious. There is a survivability bias. Good schools may look better than other schools because they are better at enrolling, separating and retaining the higher performing students, and the poorer performing students move away from the school. Educational studies almost never control for survivorship bias.

Any educational information to be useful to parents has to allow them to choose a school that would benefit THEIR child. The current state of educational information about schools does not offer information to anyone that allows changes to be made to a school to improve its performance for any fixed student body. Yes, school scores can be improved but it is often by selecting a better performing group of students for testing and not by actually improving student performance. If it were easy to make improvement changes or if people really knew, what changes to make to improve schools, student outcomes at all schools, even poor performing schools, would be improved a long time ago.

The data is unreliable for recommending changes to schools to improve student outcomes and that is why student performance is deteriorating in many schools. It is also why every recommendation that has come out of previous data studies has failed to produce the desired results of significantly improving student test score outcomes.

I posted an almost identical comment on Core economics blog, "What has transparency ever done for us?" by Joshua Gans.

Sunday, January 24, 2010

Midwest Cooling From Crop Irrigation

From 1970 through 2009, average high temperatures at the sites in Iowa and Illinois during July and August were between 0.5 and 1.0 degrees F (0.28 and 0.56 degrees C) cooler than they were for the years 1930 through 1969, the researchers found. The amount of precipitation received in the region has changed substantially as well: Average rainfall for July and August from the 1970s through 2009 was about 0.33 inches (0.8 centimeters) higher each month than it was from the 1930s through the 1960s.

[David] Changnon suggested that fewer hot days and more precipitation are linked, because humid air warms more slowly than dry air does. One likely source of the extra moisture is the region’s agriculture. Plants pump vast amounts of water from surface soil into the atmosphere as they grow, and thirsty row crops such as corn and soybeans are much more prevalent in the region these days — about 97 percent of farmland is planted in those crops now, versus about 57 percent in the 1930s, Changnon notes. Also, the plants are spaced more closely now (about 30 inches apart, versus the 40-inch spacing typical in the 1930s), a trend that has boosted the numbers of water-pumping plants per acre by about 60 percent.
From "Crop irrigation could be cooling Midwest" by Sid Perkins in Science News.

States Need To Rethink How They Allocate Their Scarce Resources

When state universities run out of money to fund classes to meet the needs and interests of all their students, they need to change the way they choose who benefits and gets into the classes they want and who does not. Other state agencies that provide non-life saving programs also need to change allocation methods of their programs to their constituencies.

For example, in The New York Times article, "Students Face a Class Struggle at State Colleges" by Katherine Mieszkowski on January 23, 2010, California University students are assigned a time to register for the remaining open classes. No preference is given to a student who values an open course more highly than another student with an earlier registration time. The later registering student may out of interest or requirement place a greater value on a particular course that an earlier registering student who would be equally satisfied and happy to take a different course.

One way to have a fairer course registration would be to use an auction (or trading) process for student registrations instead of the typical time slot method. Students could be given a fixed amount of play money that they could use to bid (or buy) for an open seat in a course. At the end of the bidding (or trading) process, open seats that are left over and available could be assigned on a first come first serve basis (or some other standardized method, such as randomized alphabet of first letter, and if needed second, then third, etc of last name, or other equally fair method), to students who still need more course credit that term. After all students register, a day of trading could be allowed for students, who desire, to improve their valuation of their semester courses.

The point is that there are many auction and market experts available who could help universities and government agencies designed fairer methods to allocate course and non-life essential programs. At universities, it would be fairer in the sense that those students who place a higher value on a course than other students will get a greater chance of successfully registering for that course than the students who care less about that course. Time slot registration does not consider the educational worth of the course to the student.

Allocation methods based on a program's recipient's self-valuation of that benefit versus another benefit from the same program would be fairer to constituencies in these times of severe state budgetary constraints. Recipients given a play money amount to buy or bid for their choices of the benefits of a program would feel like they got their monies worth because they will have outbid other potential recipients and spent all their budget.

See my previous post on this topic, "What If Colleges Auctioned Classes?"

Saturday, January 23, 2010

Middle-Class Frustration

"The Context Of Middle-Class Frustration" by Doctor Zero.
The frustration of the middle class is the angry confusion of people who can appreciate the opportunities Big Government denies them. It is the anxiety of those who hear the businesses who employ them relentlessly demonized, while the ruling class is never held responsible for its foolishness, waste, and theft. It is the resentment of people who suffer through disasters that President Obama and his allies regard as opportunities. It’s the hearty distrust of a State, and its media apparatus, that declares every frigid blast of bad economic news to be “unexpected” – but expects us to believe it can predict market fluctuations, technological advances, and even the global climate.
The author, Doctor Zero, is John Hayward and he lives in Florida.

Is It Time To Allow Large Banks To Issue Private Bank Notes?

Below is a comment I posted on Econlog blog, "Too Small to Succeed?" by David Henderson.
Actually, the failure of rural banks [during the Great Depression] was ironic. In addition to Federal law, most State banking laws also prohibited intra-state and interstate banking. The common belief was that the rural banks would just send the deposits to the cities and there would be insufficient funds for farmers, etc. Laws intended to help rural areas actually hurt them during the Depression.

The decline of the agricultural workforce allowed banks to expand nationally without negative political ramifications.

Eliminating deposit insurance now is politically very difficult and the insurance is often cited as the sole cause of the moral hazard problem. Unfortunately, when federal deposit insurance was passed, private bank notes were also banned.

These private bank notes traded as currency at par or discounts based on the healthiness of the bank issuing them. Their exchange values were probably the foremost indicators of a bank's safety and soundness. The bank notes also stopped moral hazard.

As far as I know, the reintroduction of private bank notes as currency has not be studied or promoted (but my knowledge of this area of research is limited).

Could allowing banks to issue private bank notes remove moral hazard issues? Are private bank notes viable in today's economy? Could the Fed still control the money supply? SEC issuance problems?

Gift and prepaid merchant cards are like private money in many ways since insolvency and bankruptcy leave the cardholder as a general creditor of the firm. I do not know of markets that trade these cards and reflect the viability of the issuing merchant. It may be one reason bank prepaid cards, such as Visa, MasterCard and American Express have gained in popularity over private merchant cards.

Volcker Was Very Unpopular As A Fed Chairman

People forget that there was also a populist revolt against Paul Volcker when he was Fed Chairman. His tight monetary policies made interest rates were very high (21 percent prime rate). Many economists and the public at the time believed that Volcker's failure to expand the money supply delayed the economic recovery from the 1980-81 recession and caused unemployment and interest rates to remain excessively high. The public often expressed its resentment and disagreement with the Fed's policies.

People protested against the Fed's refusal to grow the money supply, "FED OFFICIALS BOOED IN CHICAGO ON RATES" by Winston Williams, New York Times, June 22, 1981

Fortunately, Reagan did not bow to populist sentiment, supported Volcker and later reappointed him. Volcker is now held in high esteem as an excellent Fed Chairman and Reagan is viewed positively for the way he backed Volcker and allowed him to continue his monetary policies to control inflation and break the stagflation cycle of the 1970s.

7 To 10 Percent Cost Increases For Large Employers Under Unmodified Senate Health Care

Should that Senate bill pass unmodified and become law, the cost of employer-provided health care for large companies would shoot up an additional 7% to 10% per year (beyond current increases) over the next decade, for a grand total of between $62.7 billion and $89.2 billion, estimates the HR Policy Assn., a group of human-resource executives at the country's largest 300 or so firms.
****
If a health-care reform bill similar to the ones in Congress is eventually passed, how will companies react? According to the HR Policy Assn., many members are already considering such actions as reducing benefits for both retirees and employees, passing on the cost of any excise tax to workers, and even delaying hiring for open positions.
From "The Bill for the Senate's Bill" by Alix Stuart on CFO.com.

10 Percent Membership Loss For Private Sector Unions In 2009

Organized labor lost 10% of its members in the private sector last year, the largest decline in more than 25 years. The drop is on par with the fall in total employment but threatens to significantly limit labor's ability to influence elections and legislation.

On Friday, the Labor Department reported private-sector unions lost 834,000 members, bringing membership down to 7.2% of the private-sector work force, from 7.6% the year before.
From The Wall Street Journal article, "Union Membership Drops 10%" by By Kris Maher.

Friday, January 22, 2010

More Union Workers In Government Than Private Sector

There are now more government union workers than private sector union workers.

Read "In Unions, Government Workers Surpass Private-Sector Workers" By Catherine Rampell in the New York Times.